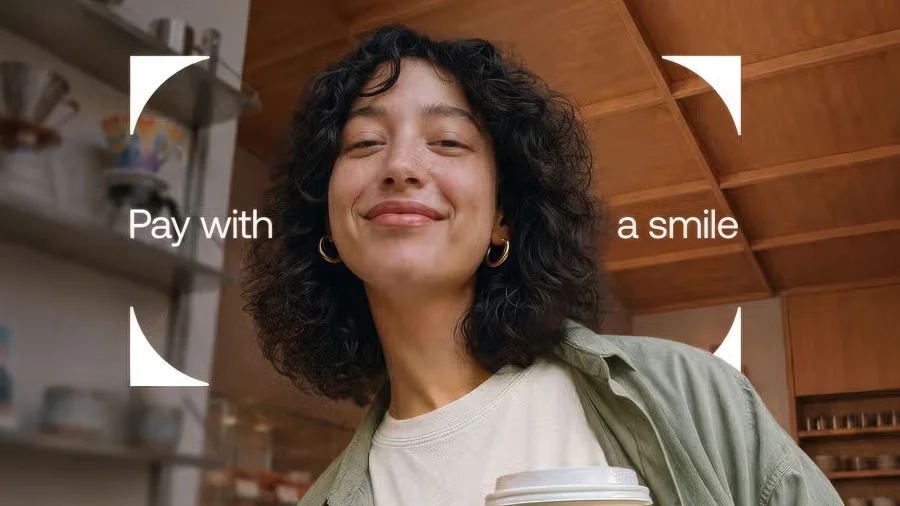
Imagine walking into a shop, picking up what you need, and paying with nothing more than a glance at a small camera. No card. No phone. No PIN. That is the future Revolut is quietly testing in the UK — and it is already dividing opinion before a single shopper has signed up.
What Revolut Is Actually Testing at the Checkout
According to the original report, Revolut is piloting a facial recognition system at store checkouts in the UK. The idea is straightforward: instead of tapping a card or unlocking a phone, a customer's face becomes the payment credential.
It is described as a trial, not a launch. That distinction matters — pilots are small, controlled and reversible. But they are also how big shifts begin.
Why Paying With Your Face Is More Than a Gimmick
For Revolut, this is about removing the last bit of friction in a payment. Cards can be lost. Phones can die. PINs can be forgotten. A face is always with you.
For shoppers, the appeal is speed — a checkout that takes seconds. For Revolut, it is a chance to own a payment method that competitors cannot easily copy, and to deepen the habit of using its app for everyday spending.
How We Got Here: Biometrics Moving From Phones to Tills
Facial recognition is not new. It already unlocks smartphones and verifies identity at some airports and border gates. What is new is the idea of using it as a routine, everyday payment method at a shop counter.
That shift — from occasional high-security checks to daily retail transactions — is what makes this pilot worth watching.
Who This Affects — and Why It Feels Different
On paper, this affects anyone who shops in the UK. In practice, it affects anyone uncomfortable with the idea of their face becoming a payment key.
Your face is not a password you can change. If biometric data is misused or leaked, the consequences are permanent in a way a replaced card is not. That is the emotional core of the debate — and it is why "convenient" and "creepy" are being used in the same sentence.
What Officials and Regulators Have Said
At the time of writing, no verified statement from Revolut, UK regulators or participating retailers was available. The pilot's scope, participating stores and enrolment process remain unconfirmed.
Until those details are public, any claim about how data will be stored, shared or deleted should be treated as speculation, not fact.
Confirmed Facts vs What Remains Unclear
Confirmed: Revolut is piloting facial recognition at UK store checkouts, per the original report.
Unclear: Which stores are involved, how many shoppers, how enrolment works, where biometric data is stored, how long it is kept, and whether customers can opt out or delete their data.
These are not minor details. They are the difference between a smart convenience and a privacy problem.
Revolut's Edge — and Why It Is Making This Bet
Revolut built its reputation on speed and product breadth — banking, cards, crypto, investing and payments in one app. That ecosystem is its moat: once a customer uses Revolut for one thing, using it for payments feels natural.
Facial checkout extends that ecosystem into the physical world. If it works, it locks customers deeper into Revolut's rails and gives the company a differentiator that card networks and rivals would need years to match.
The Risks Nobody Should Ignore
Biometric payments raise hard questions. What happens if the system misidentifies someone? What if a face is spoofed? What if data is breached?
Privacy advocates have long warned that facial recognition normalises surveillance, especially when rolled out quietly through pilots. Convenience, they argue, should not come at the cost of consent.
There is also a competitive angle: if this works, rivals will follow — and the debate will move from one pilot to an entire industry.
The Bigger Pattern: Payments Are Becoming Invisible
Cash gave way to cards. Cards gave way to phones. Now the phone itself may give way to your face. Each step traded a little privacy for a little convenience — and each step was initially controversial.
Revolut's pilot is the latest move in that long arc. Whether shoppers accept it will say as much about UK consumers as it does about the technology.
What Shoppers Should Do Right Now
Nothing urgent — this is a pilot, not a mandate. But it is worth paying attention to how enrolment is framed when details emerge.
Ask three questions before opting in to any biometric payment: Where is my data stored? Can I delete it? What happens if it leaks? If those answers are vague, wait.
What Could Happen Next
If the pilot succeeds, expect a wider rollout, likely starting with select retailers and Revolut's most engaged users. If it draws regulatory scrutiny or public backlash, expect a slower, more cautious path.
Either way, the conversation about paying with your face has now started in the UK — and it will not stay confined to one pilot for long.
Our Take
Revolut's facial recognition checkout pilot is a small trial with large implications. It shows how quickly biometrics are moving from security feature to everyday habit — and how little public debate usually precedes that shift.
The technology may well work. The harder question is whether shoppers will trust it. That answer will not come from a pilot. It will come from how transparently Revolut and its partners handle the data behind it.
Frequently Asked Questions
What is Revolut's facial recognition checkout pilot?
It is a trial in the UK where shoppers could verify payments at store checkouts using facial recognition instead of a card, phone or PIN, according to the original report.
Is paying by face safe?
Biometric payments can be secure when data is encrypted and stored properly, but risks include spoofing, misidentification and data breaches. Details of Revolut's safeguards are not yet public.
Can I opt out of facial recognition payments?
Since this is a pilot, participation is expected to be voluntary. Confirmation of opt-out and data-deletion options should come with official rollout details.
Will facial recognition checkout roll out across the UK?
Not yet confirmed. Pilots are typically limited in scope. A wider rollout would depend on results, regulatory review and public acceptance.